
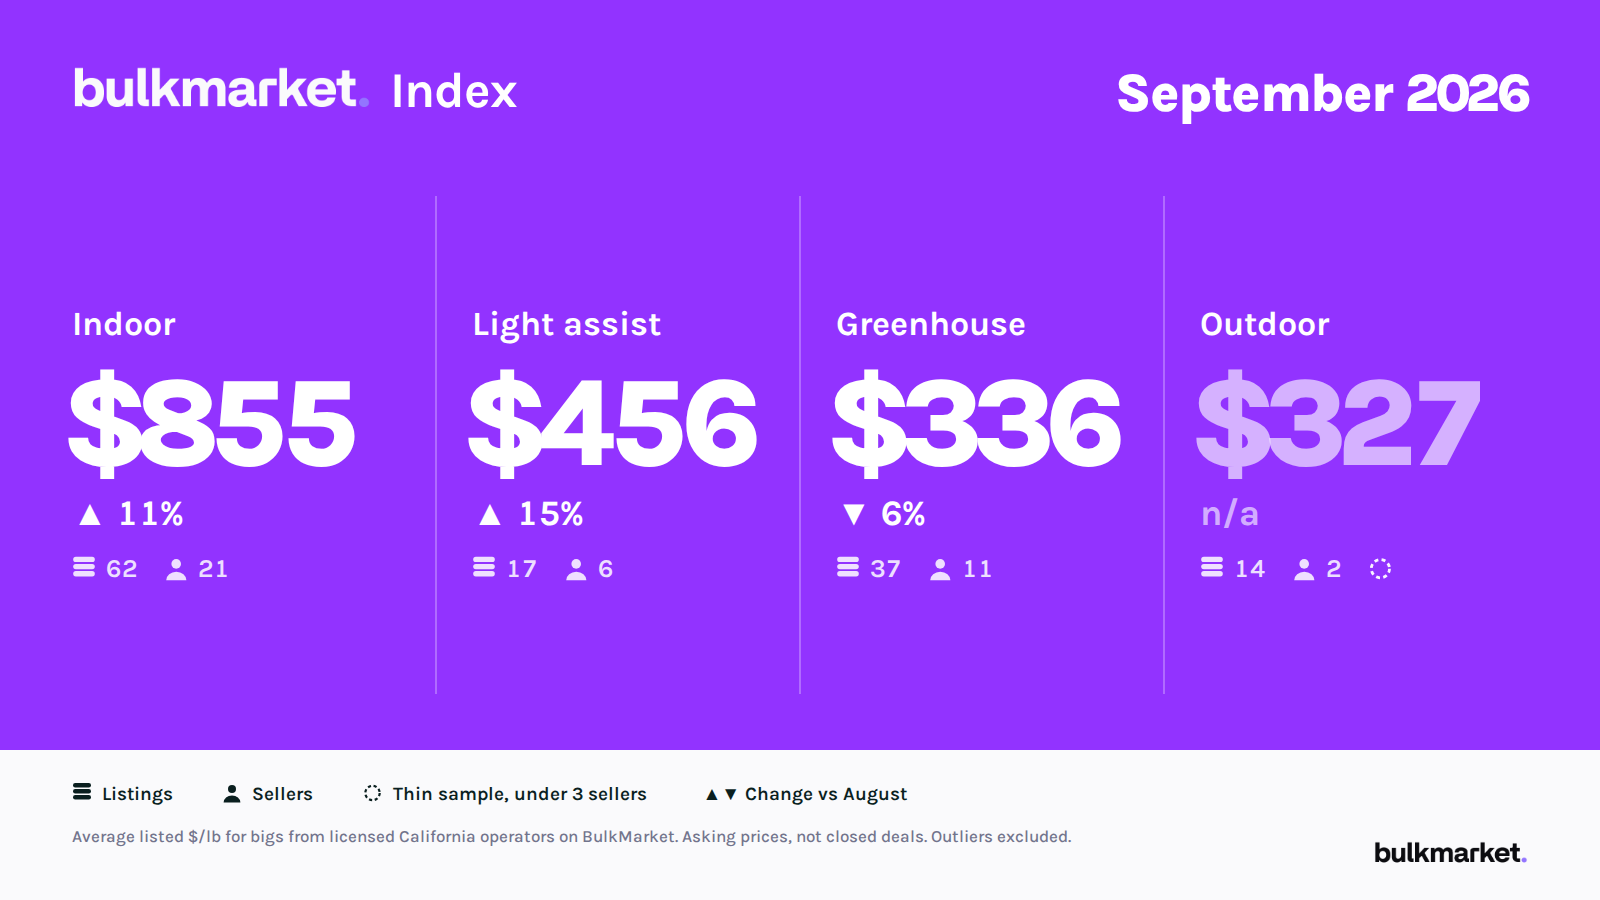
Indoor bigs listed at an average of $855/lb in September, back near the top of the range they've held all year. Greenhouse went the other way, dropping for a fourth straight month to $336/lb, about 27% below its May average.
The BulkMarket Index tracks the average asking price for bigs in the four main grow types, every month, from listings posted by license-verified California operators. It measures what operators are asking, not what deals close at, and one platform's listings are a sample of the market rather than the whole of it. Read it as a snapshot. The listing and seller counts are there so you can judge how much weight each number can carry, and we flag any category with fewer than three sellers as thin. You're welcome to share or reference the Index. Please cite it as "BulkMarket Index" with the month.
September in full
| Category | Sept avg listed | Aug avg listed | Change | Sept listings |
|---|---|---|---|---|
| Indoor bigs | $855/lb | $768/lb | +11% | 62 |
| Indoor smalls | $533/lb | $575/lb | -7% | 3 |
| Light assist bigs | $456/lb | $395/lb | +15% | 17 |
| Greenhouse bigs | $336/lb | $356/lb | -6% | 37 |
| Outdoor bigs | $327/lb | n/a | n/a | 14 |
| Greenhouse smalls | $250/lb | $263/lb | -5% | 1 |
| Light assist smalls | $225/lb | $300/lb | -25% | 1 |
| Trim | $16/lb | $13/lb | +23% | 6 |
September brought 141 new listings, down from 163 in August, the busiest month on record. Listed flower weight fell further, from about 11,900 lb to 6,800 lb, mostly because greenhouse lots got smaller.
Greenhouse: four months down
Greenhouse bigs are the clearest move in the data. The average listed price has fallen every month since May:
| Month | Avg listed | Listings | Avg lot size |
|---|---|---|---|
| May 2026 | $458/lb | 7 | 36 lb |
| Jun 2026 | $425/lb | 10 | 63 lb |
| Jul 2026 | $390/lb | 21 | 123 lb |
| Aug 2026 | $356/lb | 49 | 125 lb |
| Sep 2026 | $336/lb | 37 | 53 lb |
That's what you'd expect as greenhouse harvests come in. Listing counts climbed through the summer while prices eased, and August brought the largest lots: 49 listings averaging about 125 lb each, around 6,100 lb in total. September's lots were much smaller, averaging 53 lb. Listings alone can't tell us whether the big August lots sold or were pulled.
Buyer interest has been measured. Greenhouse bigs drew 1.7 inquiries per listing in September, below indoor (2.2) and light assist (2.8). With more lots on offer than at any point before summer, buyers in this category have room to compare.
For a reference point, greenhouse bigs listed near $290 to $300/lb last winter (December 2025 and January 2026, on small samples). September is still above that.
Indoor: back in its usual band
Indoor bigs have been the steadiest category we track. Since October 2025 the monthly average has stayed between $755 and $871/lb. July and August dipped to $776 and $768, during the heaviest indoor listing volume of the year.
September's $855 came on 62 listings from 21 sellers, the most sellers in any category in any month so far. Volume was only slightly above August's, so the rebound may reflect which lots got posted (cultivar, quality tier, lot size) as much as any change in what buyers will pay. Listing data can't separate the two.
The gap between indoor and greenhouse widened to about $519/lb. Indoor bigs listed at roughly 2.5 times greenhouse in September, up from 2.2 times in August and the widest spread since last winter.
Light assist rebounds on fewer listings
Light assist bigs had a crowded August, with 46 listings averaging $395/lb. September thinned out to 17 listings, and the average climbed to $456/lb.
Each listing got more attention. Views per listing more than doubled (25 to 54) and inquiries per listing nearly doubled (1.5 to 2.8). Fewer lots, more buyers looking at each one. Light assist is still well under its spring averages, which ran $620 to $717/lb from March through May on small samples.
Outdoor and trim
Outdoor bigs showed up with 14 listings at an average of $327/lb, more outdoor listings than in any previous month. Two sellers posted all of them, so treat the figure as those two operators' pricing rather than a read on outdoor as a whole.
Trim listed at $16/lb across 6 listings and about 1,900 lb, and drew no inquiries in September. It has ranged from $13 to $35/lb over the past year.
What buyers were searching for
Toad Venom was the most searched strain on BulkMarket in September, with Zours second.
Over the last 90 days, fresh frozen has been the most common category search. It doesn't show up in the price tables above, which cover flower and trim listings, but the timing fits: fresh frozen gets made at harvest, and processors sourcing input for live resin and rosin are looking now. Dry trim drew no inquiries this month. Search counts show interest rather than purchases, but the contrast is worth watching for anyone with harvest material.
Trends, and what October could bring
This section puts the month in context and makes a read on October. It's our interpretation of listing data and published indexes, not a forecast, and we'll check it against October's numbers next month.
| Index | September | Jul to Sep avg | 12-month avg | Last three months |
|---|---|---|---|---|
| Indoor bigs | $855 | $804 | $818 | Dipped, then recovered |
| Light assist bigs | $456 | $415 | $475 | Down, then up on fewer listings |
| Greenhouse bigs | $336 | $356 | $361 | Down every month |
| Outdoor bigs | $327 | $317 | $306 | Too few sellers to call |
On the demand side, inquiries per listing have fallen as supply grew. In April, 23 listings drew 5.4 inquiries each. By August and September, with six to seven times as many listings, that was down to about 2. Platform activity grew over the same stretch, but listings grew faster, so each lot is competing for a smaller share of attention.
Croptober
Most of California's outdoor crop comes down over the next several weeks. For outdoor farms this is the one harvest of the year, and the work that goes into it shows up in what gets listed this winter.
In the listings, harvest usually lands later than the calendar suggests. Fresh frozen moves right away. Dried flower has to dry, cure, get trimmed and clear testing before it's listed as finished product, so the heaviest outdoor supply tends to reach the market in November and December rather than October.
Last year's national numbers show that lag. The U.S. Cannabis Spot Index published by Cannabis Benchmarks climbed through summer 2025 and peaked at $1,200/lb in early October, then fell 4% to $1,119 by mid-October and eased through the end of the year. The timing isn't fixed: in 2023 the same index kept climbing through October and much of November before its seasonal decline started.
| Report date | Spot Index ($/lb) | Weekly change |
|---|---|---|
| Jan 3, 2025 | $888 | -4.8% |
| Feb 7, 2025 | $923 | -3.3% |
| Mar 7, 2025 | $1,011 | +5.6% |
| Apr 4, 2025 | $936 | -4.2% |
| May 2, 2025 | $944 | -3.0% |
| Jun 6, 2025 | $1,034 | -0.1% |
| Jul 4, 2025 | $1,100 | +1.8% |
| Aug 1, 2025 | $1,135 | -1.0% |
| Sep 5, 2025 | $1,055 | +1.6% |
| Oct 3, 2025 | $1,200 | +0.3% |
| Nov 7, 2025 | $1,120 | -1.2% |
| Dec 5, 2025 | $1,093 | +1.5% |
The Spot Index is national, covers all grow types and is built from a different methodology, so its dollar levels aren't comparable to the BulkMarket Index. The shape is what's useful. Outdoor has also taken the steepest long-run price decline in California: a DCC-published market outlook put inflation-adjusted outdoor wholesale prices down 74% from their 2020 peak by late 2024, against 46% for indoor.
Our read for October
Indoor is the least exposed to harvest season. It has held a $755 to $871 band for a year, and we'd expect October inside it. September's $855 sits near the top, so a move back toward the 12-month average of about $820 wouldn't signal much. The indirect risk is buyers shifting some volume to cheaper sun-grown as it lands.
Greenhouse is where we'd expect the most pressure. Full-term greenhouse and outdoor harvests overlap, the index has already fallen four months running, and its inquiries per listing are the lowest of the three larger categories. A fifth decline wouldn't surprise us. Last winter's listings, near $290 to $300/lb, are the closest reference point for where that could settle.
Light assist could go either way. September's rise came on a third of August's listings. If more lots post in October, some of that gain likely comes back. If supply stays thin, it has room to hold near its 12-month average of about $475.
Outdoor should get its first real read in November rather than October. We'd expect listing and seller counts to climb late in the month as dried flower clears testing. Last winter's outdoor bigs listed around $290 to $310/lb on small samples, which is the only comparable we have.
Fresh frozen and trim will likely keep moving in opposite directions for a few more weeks: fresh frozen searches at harvest peak, dry trim quiet.
A few things would change this read: greenhouse listing counts falling sharply, inquiries per listing climbing back toward 3, or outdoor lots arriving earlier and in larger volume than usual. We'll report what October shows either way.
On the network
A few numbers on who is behind the listings. 158 license holders were active on BulkMarket in September, an all-time high and up every month since September 2025. 29 recurring sellers (operators who posted in September and in an earlier month) listed this month, also a record, with growth every month since April. About 60 buyers were active in September.
The network added 24 verified operators in September, 14 of them buyers, for 390 total. Operators sent 617 messages during the month.
How the BulkMarket Index works
- The Index covers bigs in four grow types: indoor, light assist, greenhouse and outdoor. Each value is the average listed $/lb across that month's listings, not weighted by pounds.
- Prices are listed or asking prices, not closed deal prices.
- Listings with outlier prices are excluded from the averages. In September, 8 listings were excluded across all categories.
- Change compares each value to the previous calendar month. When a category had no listings that month, no change is shown.
- Listing and seller counts are shown for every value. Fewer than three sellers is marked as a thin sample.
- Inquiries are counted each time someone taps the message button on a listing. That makes them a gauge of buyer interest, not a count of messages delivered or deals discussed.
- September covers listings posted September 1 to 30, 2026. Only BulkMarket listings are included, so operators who don't list here aren't captured.
If your September deals looked different from what's here, we'd like to hear about it at support@bulkmarket.app.